Author: pebblewriter

  • Now or Never?

    According to Missouri Republican Roy Blunt, “If we’re going to do it this year, I think it’s now or never.”  Of course, a $2 trillion package will face stiff opposition in the Republican Senate, especially with more and more senators prudently distancing themselves from President Trump.

    The bond market is torn on whether or not to believe it, with the 10Y again testing overhead resistance. And ES, which tagged our next downside target after hours yesterday, isn’t very optimistic at all.continued for members… (more…)

  • Update on Currencies: Oct 21, 2020

    For the past several months, we’ve been patiently waiting for DXY’s next leg down. Given the importance of preventing a EURUSD breakout, it seemed apparent that USD weakness would need to come courtesy of JPY strength. Today, push finally came to shove.

    The implications for equities are significant.

    continued for members… (more…)

  • Housing Boom: 2007 Redux

    Single-family home starts continued to gain from rock bottom interest rates and the exodus from urban, multifamily housing amid the pandemic. September residential starts grew 1.9%, while permits rose 5.2%, the fastest since the 2007 peak.

    Single-family inventory dipped to 3.3 months, the smallest since 1963, while multifamily starts cratered by 16.3%.

    It was a bright spot of economic news following an ugly day of losses across all indices yesterday that saw ES tumble to our next downside target.

    continued for members… (more…)

  • Charts I’m Watching: Oct 19, 2020

    Futures are higher ahead of the open on a slight increase in interest rates and the usual algo-baiting such as USDJPY’s latest bounce.

    continued for members… (more…)

  • Retail Sales’ Last Hurrah?

    September retail sales sharply beat estimates, coming in at +1.9% versus 0.8% expected. With enhanced unemployment and virtually all other stimulus having dried up, however, this could be retail’s last hurrah.

    But, it’s enough to boost stock prices on this OPEX Friday 2 1/2 weeks before a presidential election.

    continued for members… (more…)
  • The Pandemic’s Stark Reminder

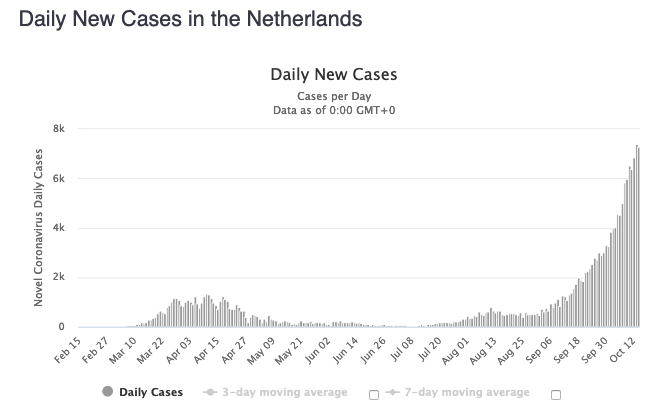
    Futures tagged our initial downside target overnight as markets are once again reminded that the pandemic is far from over.

    The shutdown headlines out of Europe won’t surprise anyone who has been watching the COVID-19 numbers.

    The US, which was considerably less successful in suppressing cases following the initial or second surge, is on the same path – but from a much higher base.

    continued for members… (more…)

  • Charts I’m Watching: Oct 14, 2020

    Futures are slightly higher ahead of the open after tumbling as many as 49 points from Monday’s highs.This, despite a sharp rally in oil ahead of the holiday delayed EIA inventory report and a (barely) bearish cross in VIX. The algos are getting nervous.

    continued for members… (more…)

  • CPI: Putting the Brakes On

    CPI rose 0.2% MoM in September, half the August rate. It rose 1.4% YoY, slightly higher than September’s 1.3%. Without the outsized gains in used cars and the minor gains in energy (conflicting with the official EIA data), MoM CPI would likely have been negative.

    This is hardly supportive of the reflation narrative driving equity prices lately. This should be the last straw for the 10Y’s bounce, with the resulting breakdown a significant headwind for stocks.

    continued for members… (more…)

  • A Cure?

    Despite the number of US coronavirus cases nearing 8 million and deaths approaching 220,000, the algos continue to focus on their daily dose of collapsing VIX.

    It’s enough to make one wonder whether central bankers have found a cure for a market correction.

    continued for members… (more…)

  • The Beat(down) Goes On

    VIX’s beatdown continues to nudge algos higher, finally dropping through its Sep 16 lows.

    continued for members… (more…)