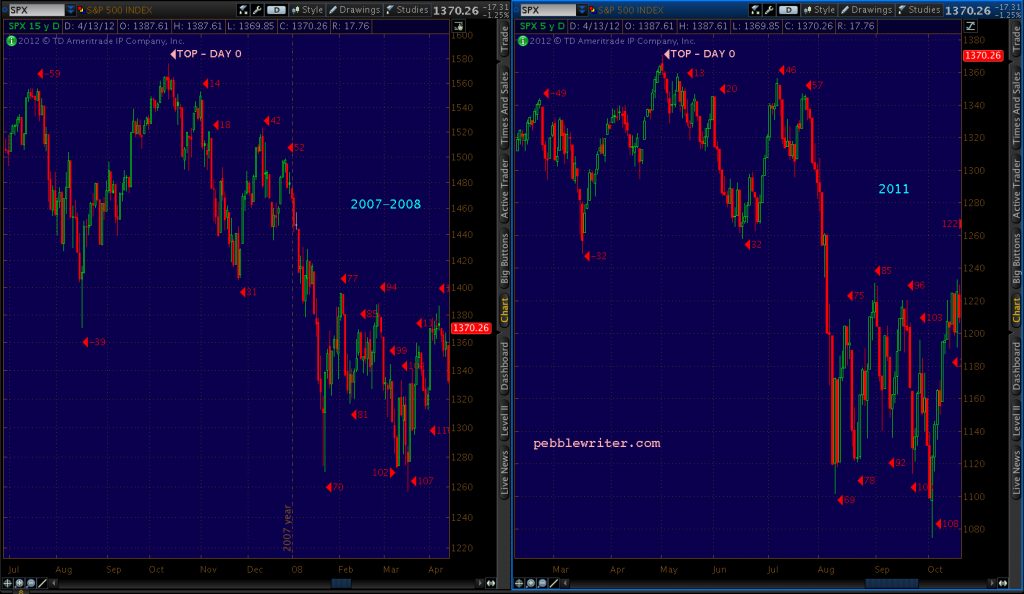
Futures are up modestly ahead of the open, with consumer confidence due at 10AM.
 continued for members… (more…)
Futures are up modestly ahead of the open, with consumer confidence due at 10AM.
continued for members… (more…)
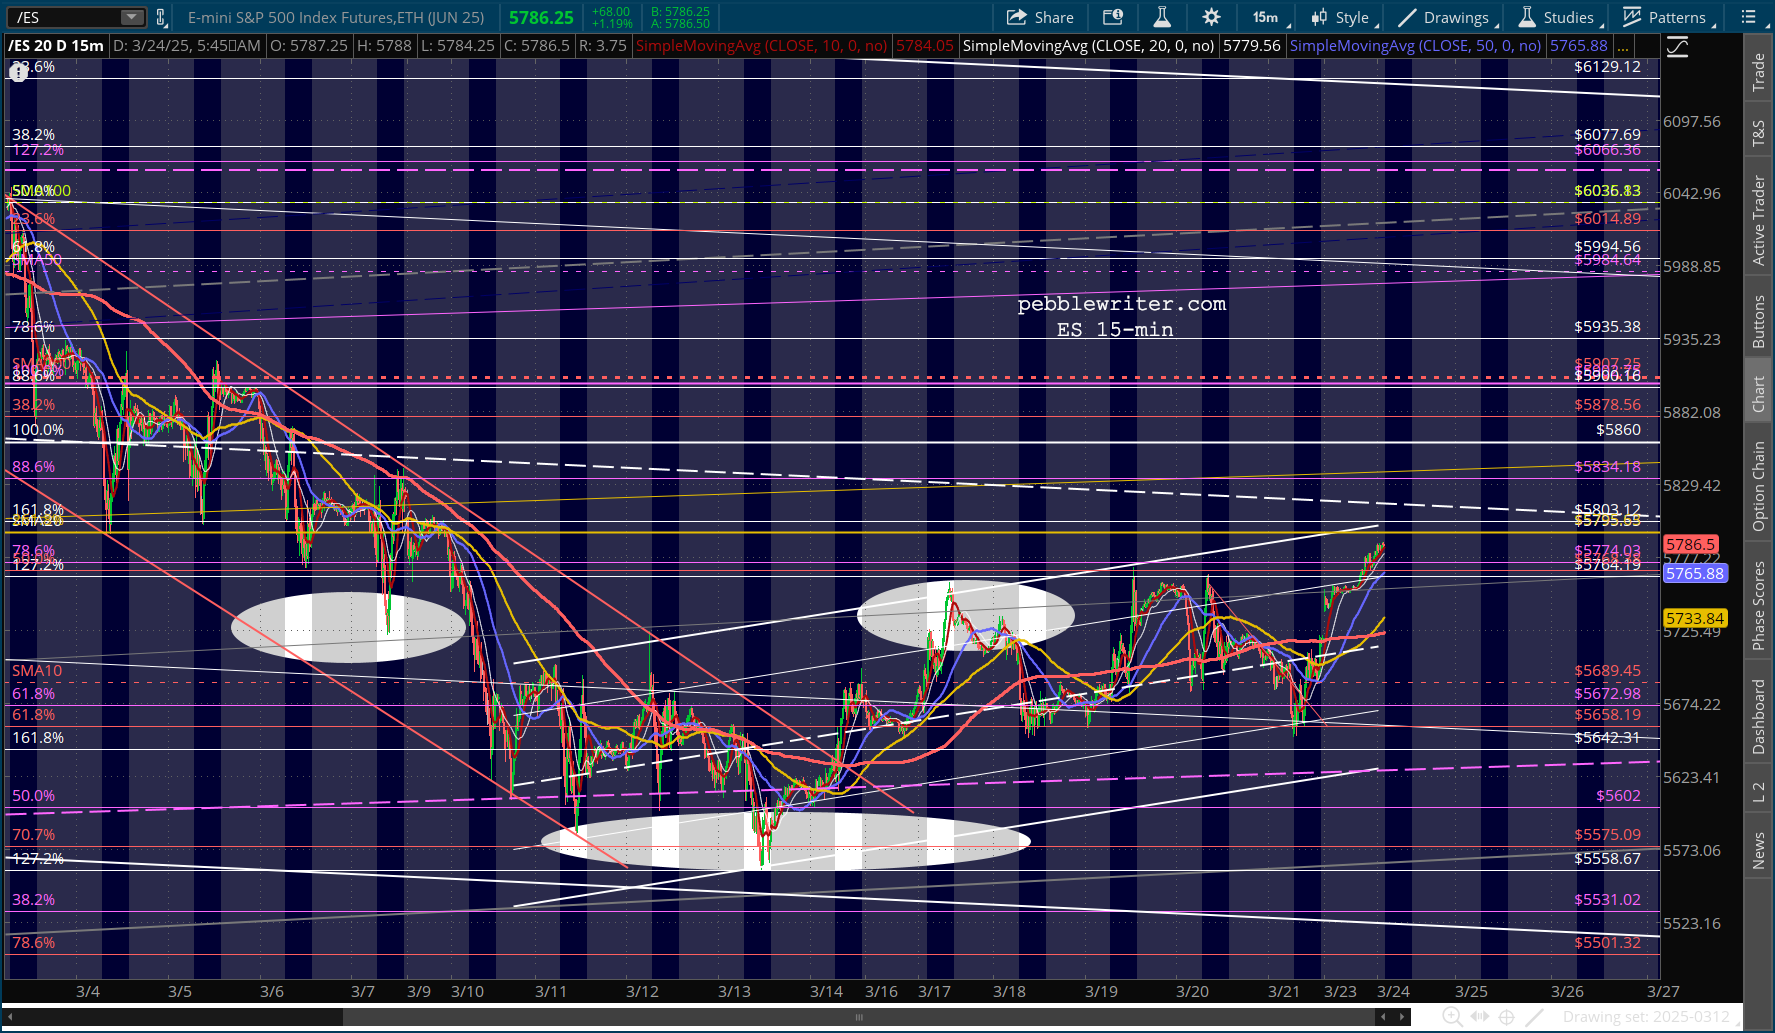
Futures are up sharply after Trump took stock of the tanking market’s reaction to tariff developments and suggested that they might not be as pervasive as he had previously insisted.
It’s just the latest effort to ramp futures in the after hours using the 2017-21 playbook: start a fire and then brag about putting the fire out.
 continued for members… (more…)
Six weeks ago [see: Gold’s Inflation Warning] we noted that GC was approaching the 3012.80 target we set in April 2024. Its ascent was an indication not only that inflation prints were likely to be worse than expected, but that the equity market faced rough times ahead.
SPX’s very obvious negative divergence strongly suggests that the index had no business making its recent new highs.
As it happened, SPX proceeded to tumble over 10% from those highs. It’s troubling, then, that GC soared right through its 3012.80 target and is approaching our next upside target.
 It’s even more troubling that this is happening at a time when many equity investors have taken Powell’s soothing tone as a signal to jump back on the permabull bandwagon – despite the downright scary charts we’re seeing in equities.
 Dovish Chicago Fed president Austen Goolsbee said the quiet part out loud this morning on CNBC. Stagflation is a very real concern, and one that the FOMC has little chance of mitigating.
continued for members… (more…)
The market’s reaction to yesterday’s FOMC decision was, quite simply, overdone. Equity indices were initially firm, but popped on a swift drop in vol. Did lowering the amount of QT help? Perhaps.
But, Powell readily admitted that FOMC members have no idea where employment and inflation are headed. Inflation estimates are higher and growth is expected to slow. So, we’ll stick with our own assessment: stagflation.
 continued for members… (more…)
Futures are modestly higher as we approach the open and an FOMC decision which will hopefully shed light on the Fed’s thoughts about the economy.
 continued for members… (more…)
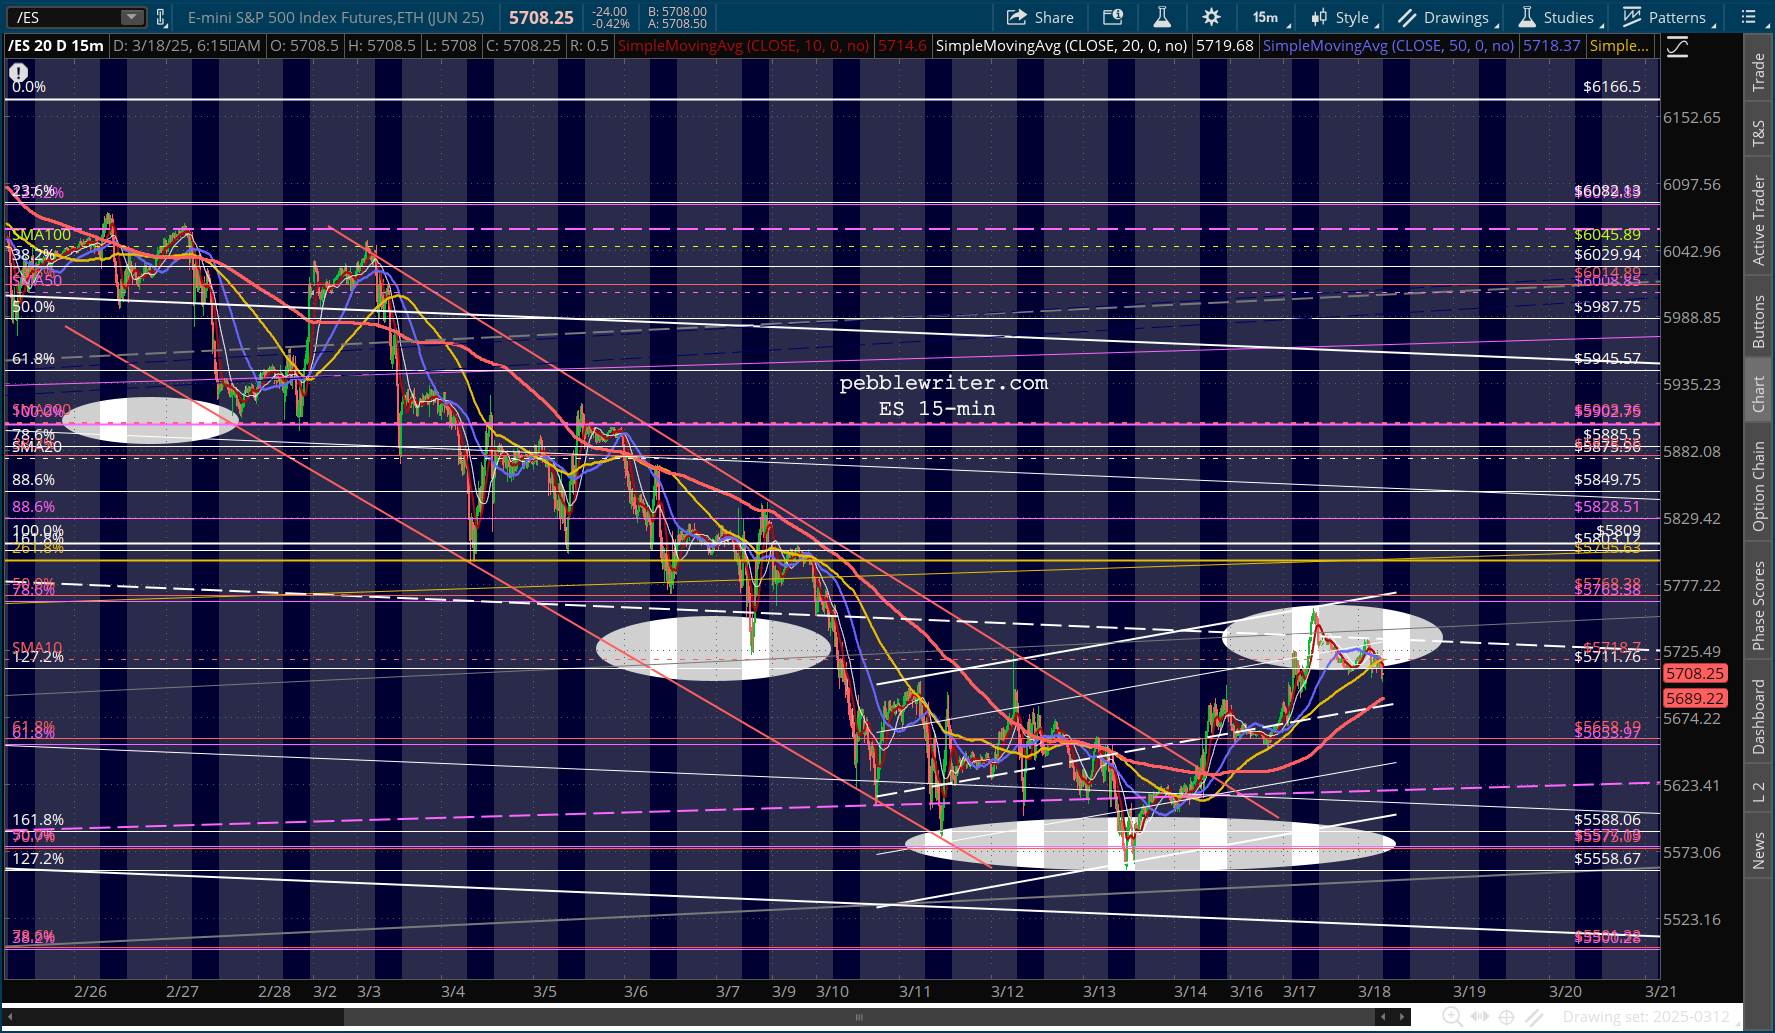
Futures are off moderately on the eve of the next FOMC rate decision.
 continued for members… (more…)
Retail sales and Empire State Mfg both came in worse than expected, meaning there’s an improvement to the odds of a fed rate cut – or so the thinking goes.

Markets were off a bit over the weekend, due in part to Bessent’s comparison of current conditions to 2006-2007, but the weak economic data brought futures back to flat.
continued for members… (more…)
We’ve seen countless overnight rallies over the past month. Some of them carried over into the regular sessions, but most of them were faded.
Yesterday’s plunge took SPX all the way to a key channel midline and Fib retracement and was followed by a 50-pt overnight ramp job, leaving ES at a key overhead resistance. With a Fed meeting coming up next week and a shutdown (potentially) averted, does this bounce have legs? continued for members… (more…)
Ordinarily, investors might prefer lower CPI and PPI. But, so far, the market hasn’t reacted well. Why not?
Sure, lower prices might give the Fed room to reduce interest rates and thereby goose the stock market. But, you have to ask “why” prices aren’t going up as quickly as before.
Is it because corporations don’t have pricing power? Is it because consumers aren’t liquid enough to shop with abandon? Or, maybe the lower data aren’t really indicative of what consumers are seeing in the supermarket?
In any case, futures got a very small bump after Feb PPI data were released this morning. This follows a nice bump from yesterday’s CPI that was immediately faded as investors still realize that Trump’s tariff policies are, as CNBC economics reporter Steve Liesman labeled them, insane.
 The decline in inflation is exactly what our gas model suggested would happen. If gas prices were to remain level, we would expect CPI to continue falling.

continued for members... (more…)
CPI drifted lower in February, coming in below consensus at 0.2% MoM and 2,8% YoY. Core was also 0.2% MoM and registered 3.1% YoY. The print was in line with our model, which also suggested a bounce yesterday, Futures, initially up 1.5%, are indicating a still strong 1% higher.
 continued for members… (more…)