…and, the market soars! Just because.
There’s another old economics joke:
Q: How many central bankers does it take to change a light bulb?
A: None. It’s getting brighter, see? It’s definitely getting brighter!
The brain trust which has overseen the Fed since 2006 assembles today at the American Economic Association’s annual meeting. We’ve all seen the data: expansion of the Fed’s balance sheet from $800 billion to $4.4 trillion; a stock market which rallied 340%; 10Y notes which fell from 5.3% to as low as 1.3%; fed funds rate which fell from 5.25% to as low as 0.04%.
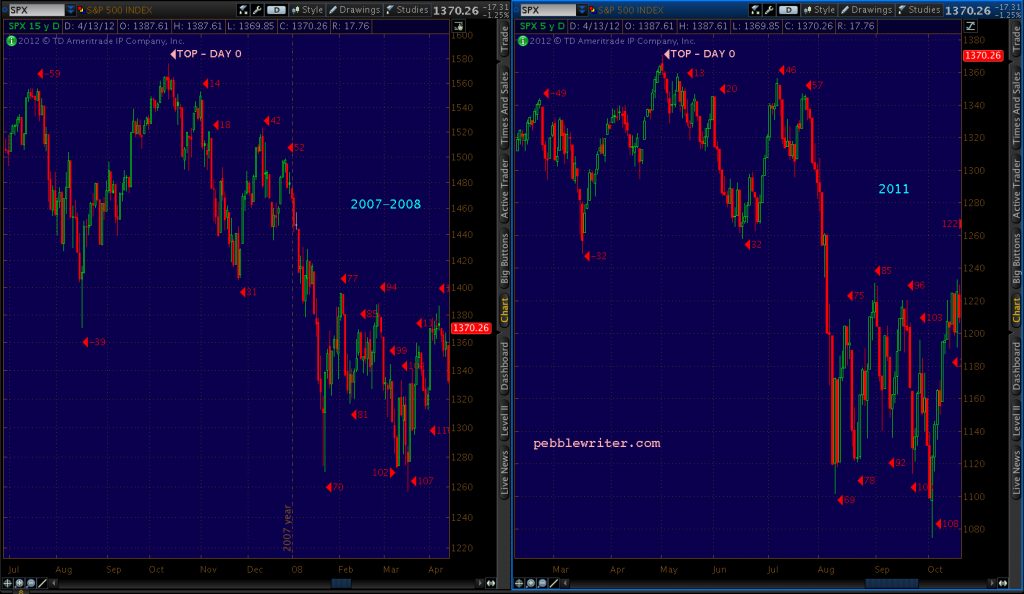
Bernake and Yellen obviously oversaw some sizeable market declines – Bernanke’s 57% 2007-2009 freefall obviously dwarfed Yellen’s carefully managed 15% swoon in 2015-2016.
But, it’s Powell’s 20% (so far) 2018-2019 correction that is attracting all the attention, as it is viewed by many as the result of a policy mistake. During his short tenure, Powell has already presided over two breakouts in rates (the solid red trend line, followed by the dashed purple trend line) and, in the past couple of weeks, a breakdown in rates (the dashed red TL.)
 The breakouts alarmed many as they had a significant and immediate impact on industries which rely on low rates for prosperity: housing, autos, etc. They also refocused attention on the US’ disastrous debt imbroglio. The increase in rates (the black line) will be enough to help turn a 5% increase in federal debt into a 13% increase in interest expense.
 The problem is that thanks to the algo-inspiring spike in oil and gas prices last year, inflation was becoming a problem and justified higher rates. Since October, oil and gas prices have tumbled. December CPI will likely come in near 2% or even less. Both extremes were manipulated, as even Trump has now admitted.
 So, what metric should the Fed pay attention to in deciding the course of future hikes? Slumping real estate sales and ISM surveys? Strengthening employment figures? It seems Powell is damned if he does and damned if he doesn’t.
I suspect we’ll see smiles of relief from Bernanke and Yellen who got out while the getting was good.
Last night we got a pretty typical pre-Fed ramp job. When you see the futures do this… …there’s usually a reason, such as the corresponding ramp job in oil.
 The momentary hiccup when the 312K jobs number was announced was easily offset by hammering VIX from where it was when I began this post two hours ago…
 …to here.
 And, suddenly, everything is getting brighter!
 If you’re wondering why the ramp job stopped after 37 points, it’s pretty simple. That’s all that was needed to get SPX up to and over its SMA5 200 at which point the algos will have free rein. If Powell’s comments aren’t dovish enough, stocks will have a nice cushion.
 I wonder if all those people who were complaining about algorithms deflating the stock market will be upset when they produce a rally?
continued for members… (more…)


 continued for members…


 …and CL, which bounced off the channel bottom it was backtesting.

 It’s not usually so obvious. The reality is that the guys who usually push the buttons and pull the levers behind the curtain are all off on vacation.
 The first factor was oil, which saw a channel which dates back to Feb 11, 2016 break down on Monday. It closed below the channel bottom – quite bearish.
 Yesterday, it recovered sharply — rallying 10.95% from Monday’s lows. Note that it bottomed where ES did at “1”, pulled back a bit at “2” when ES backtested its SMA5 200 (a frequent support level for algorithms), and didn’t let up until it reached “3” at the same time as ES.
 The second was VIX, which on Monday had closed above the .618 Fibonacci retracement of the drop from 50.3 in February to 10.17 in August. This was a potential turning point. So, the fact that it closed above the .618 on Monday was quite bearish.
 Despite having closed above the .618 (point 1), it dipped below it and broke below the rising purple trend line at exactly the same time that ES first climbed above its SMA5 200. It backtested the TL when ES backtested its SMA5 200 (point 2) and plunged 18.3% over the next 6 hours — conveniently bottoming out (after breaking below the red TL as well) at the close (point 3.)

 Yesterday, it had worked its way below the .886 again prior to the market opening, then sharply recovered by the time the market closed. As with the others, its inflection points exactly matched those of ES.
 The big question on everyone’s mind is whether the correction is over. Have we avoided a bear market? Our charts have shown that lower lows would come ideally in February or even March.


