Wishing everyone a very, Merry Christmas and a healthy, peaceful and prosperous 2024.

***
We’ll be back at the end of the week with a review of 2023 and look ahead at next year.
Wishing everyone a very, Merry Christmas and a healthy, peaceful and prosperous 2024.
***
We’ll be back at the end of the week with a review of 2023 and look ahead at next year.
PCE came in below expectations. Headline was -0.1% MoM and 2.6% YoY. Core was +0.1% and 3.2% YoY. This was the smallest rise since April 21, and offers the Fed additional room to consider cuts in 2024 should the trend continue. Futures added to modest gains after the print. The key issue remains: whether the moderating inflation trend can continue unabated.
continued for members… (more…)
We finally saw the backtest we’ve been expecting as SPX fell a whopping 70 points (-1.47%), almost reaching its 10-day moving average and bleeding off its overbought condition.
 ES came within a few points of our Fibonacci backtest, also coming up just short of its 10-DMA.
 continued for members… (more…)
Futures were off moderately after disappointing Fedex earnings/outlook and in advance of consumer confidence and existing home sales, both due out at 10am ET. Despite strong prints that argue against rate cuts, stocks are back in positive terrritory. Maybe we’ll finally get that long overdue backtest. SPX closed yesterday at one of the most overbought levels in almost 30 years.
 continued for members… (more…)
In a move that surprised no one, the BoJ left their monetary policy unchanged unhinged. The policy statement still reflects the looney tunes, magical thinking that has always epitomized their decisions: they’ll raise rates when inflation reaches 2% – even though inflation is well above 2% and has been for over a year.  Annualizing the past quarter, CPI is running at 5.4%. Yet, the BoJ is holding short term rates at -0.10% and the 10Y at 0%. Ultra-low interest rates have exacerbated the inflation problem for consumers, as the yen continues to hover near 30+ year lows – driving food and energy prices even higher.
 However, increasingly squeezed consumers remain at the bottom of the BoJ’s priority list, along with Debt:GDP – currently around 255%. At the top of the list: the Nikkei 225 stock index – hovering near all-time highs.
continued for members… (more…)
Futures are drifting higher as we approach the open, mostly on year-end positioning.
 continued for members… (more…)
If Jay Powell’s comments were intended to spur the market to new highs, NY Fed President John Williams’ were intended to slow the roll. On CNBC this morning:
“We aren’t really talking about rate cuts right now…we’re very focused on the question in front of us, which as chair Powell said… is, have we gotten monetary policy to sufficiently restrictive stance in order to ensure the inflation comes back down to 2%? That’s the question in front of us.”
Futures were not amused, dropping from slightly higher to slightly lower as he spoke even though today is OPEX [see: Does OPEX Matter? (which desperately needs updating)].
 continued for members… (more…)
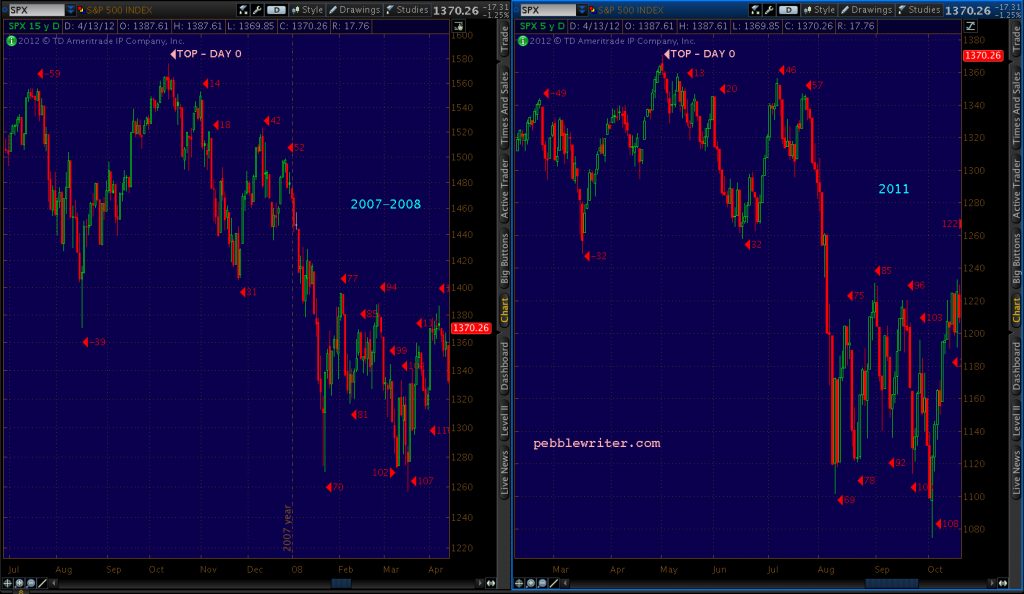
Okay, he didn’t actually say that. But, he might as well have. His latest press conference was completely devoid of any hawkish sentiment. Not only did SPX shoot up past our year-end target… …the 10Y plunged to our downside target.
 The message was clear. Interest rates are coming down and the Fed’s third mandate (higher stock prices) is officially in play, with all-time highs are right around the corner. But, are they?
We don’t wish to sound negative, so we’ll let Goldman Sachs’ 2024 Equity Outlook do it for us. Stocks might be near record highs, but it’s really just the magnificent 7 which are reaching rarified air. The rest…not so much.
 continued for members… (more…)
With CPI notching only slightly higher than expected yesterday and PPI coming in plenty low (0.0% MoM, 0.9% YoY) the FOMC will have a difficult time convincing algos that there isn’t a rate cut coming in the spring.
Futures continued their meltup… …driven largely by VIX’s repeated meltdown.
 Ramp it up overnight so you can hammer it just prior to the opening the next morning. Works every time…
 continued for members… (more…)
CPI came in slightly hotter than expected at 0.1% versus 0.0% expected and prior (annual 3.1% vs 3.1%.) Core was 4.0% (unchanged) but 0.3% monthly versus 0.2% prior and 0.0% expected.) Core goods actually fell 0.3% while much stickier services rose a blistering 0.5%. This is all a bit of a disappointment for the rate cut crowd.
 Futures are off slightly.
 continued for members… (more…)