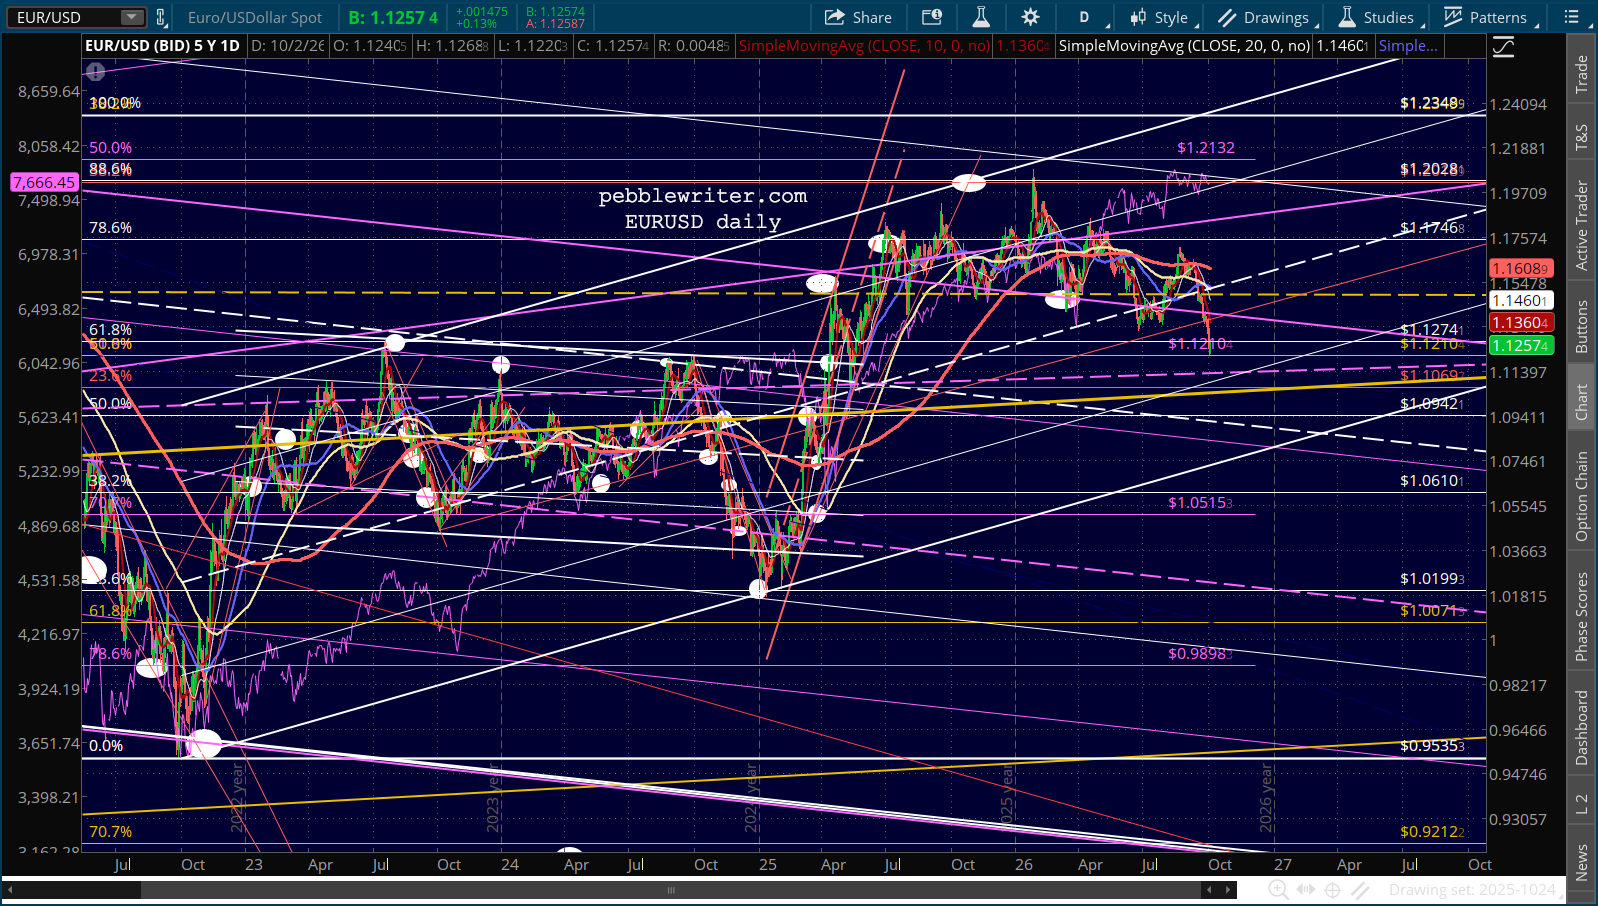
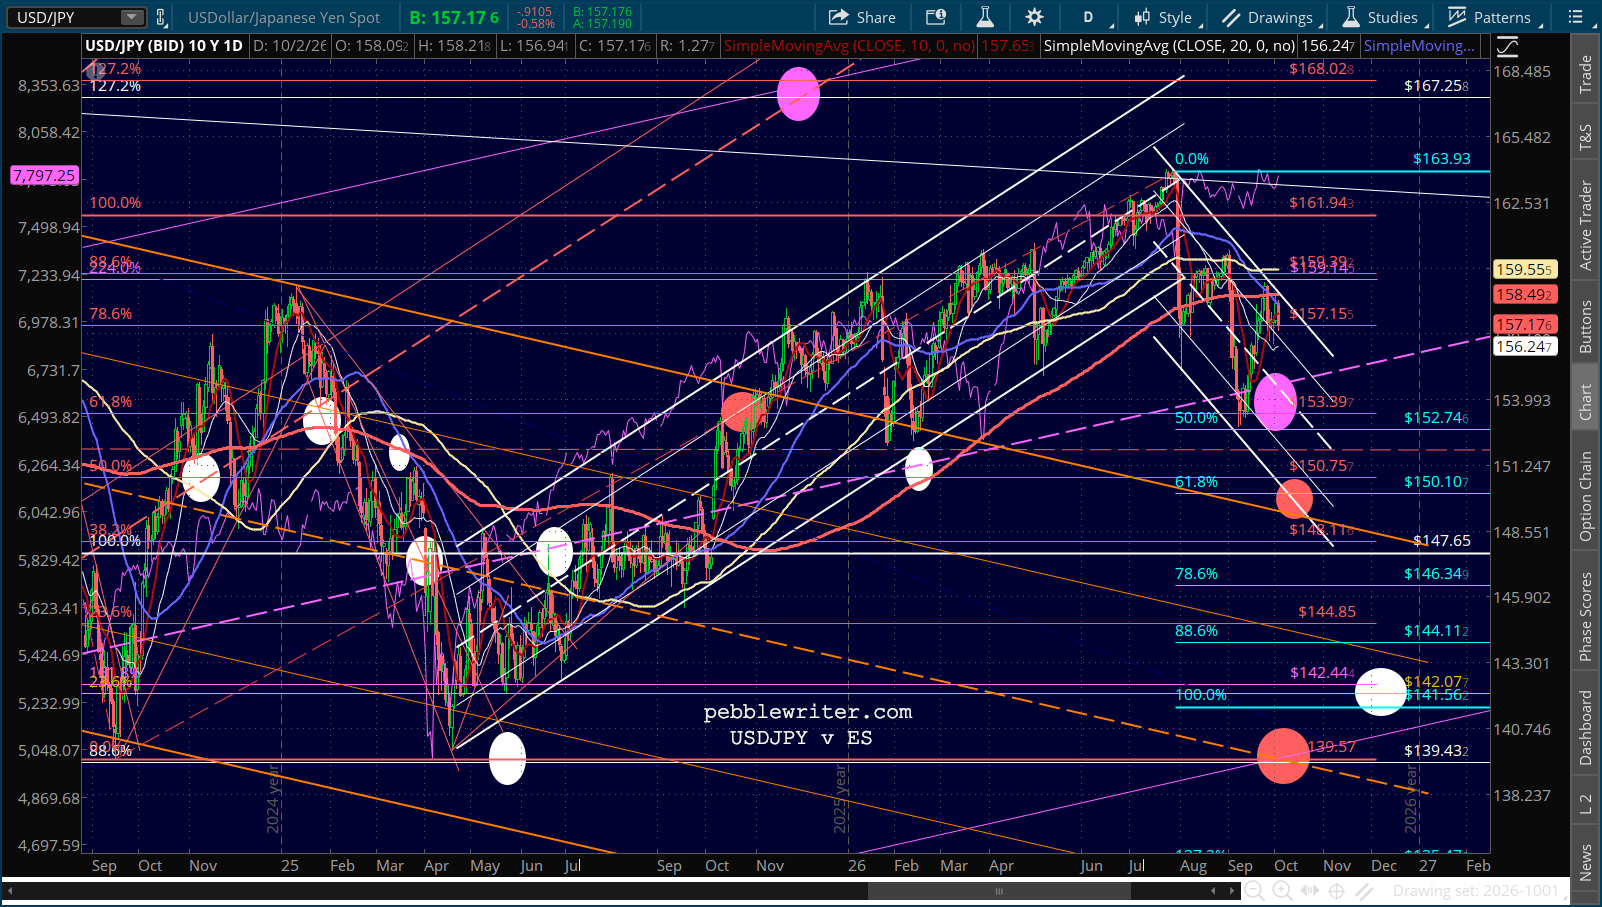
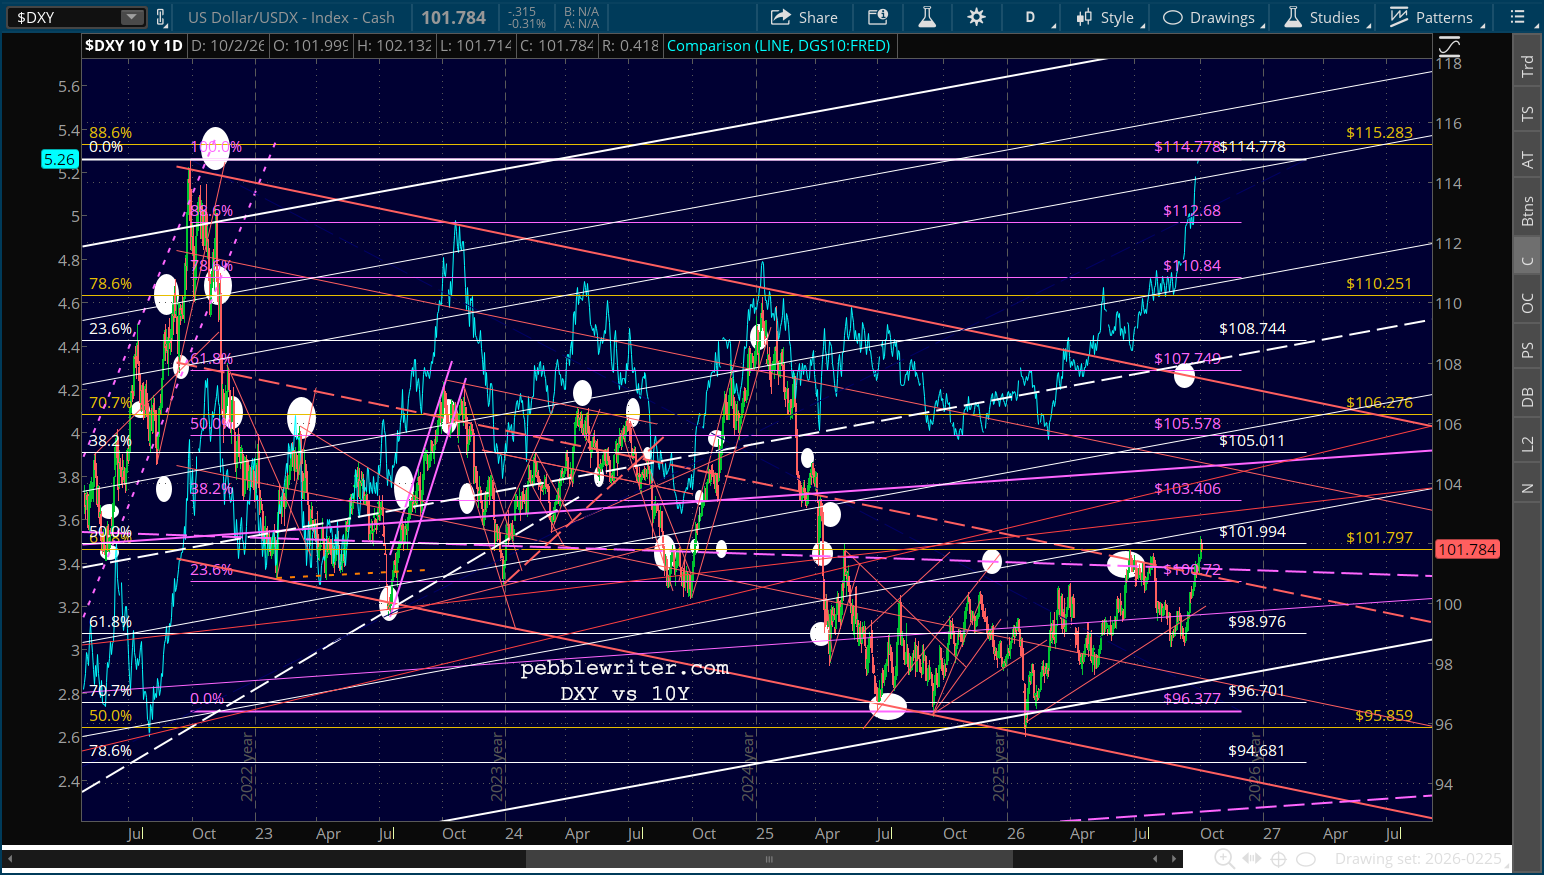
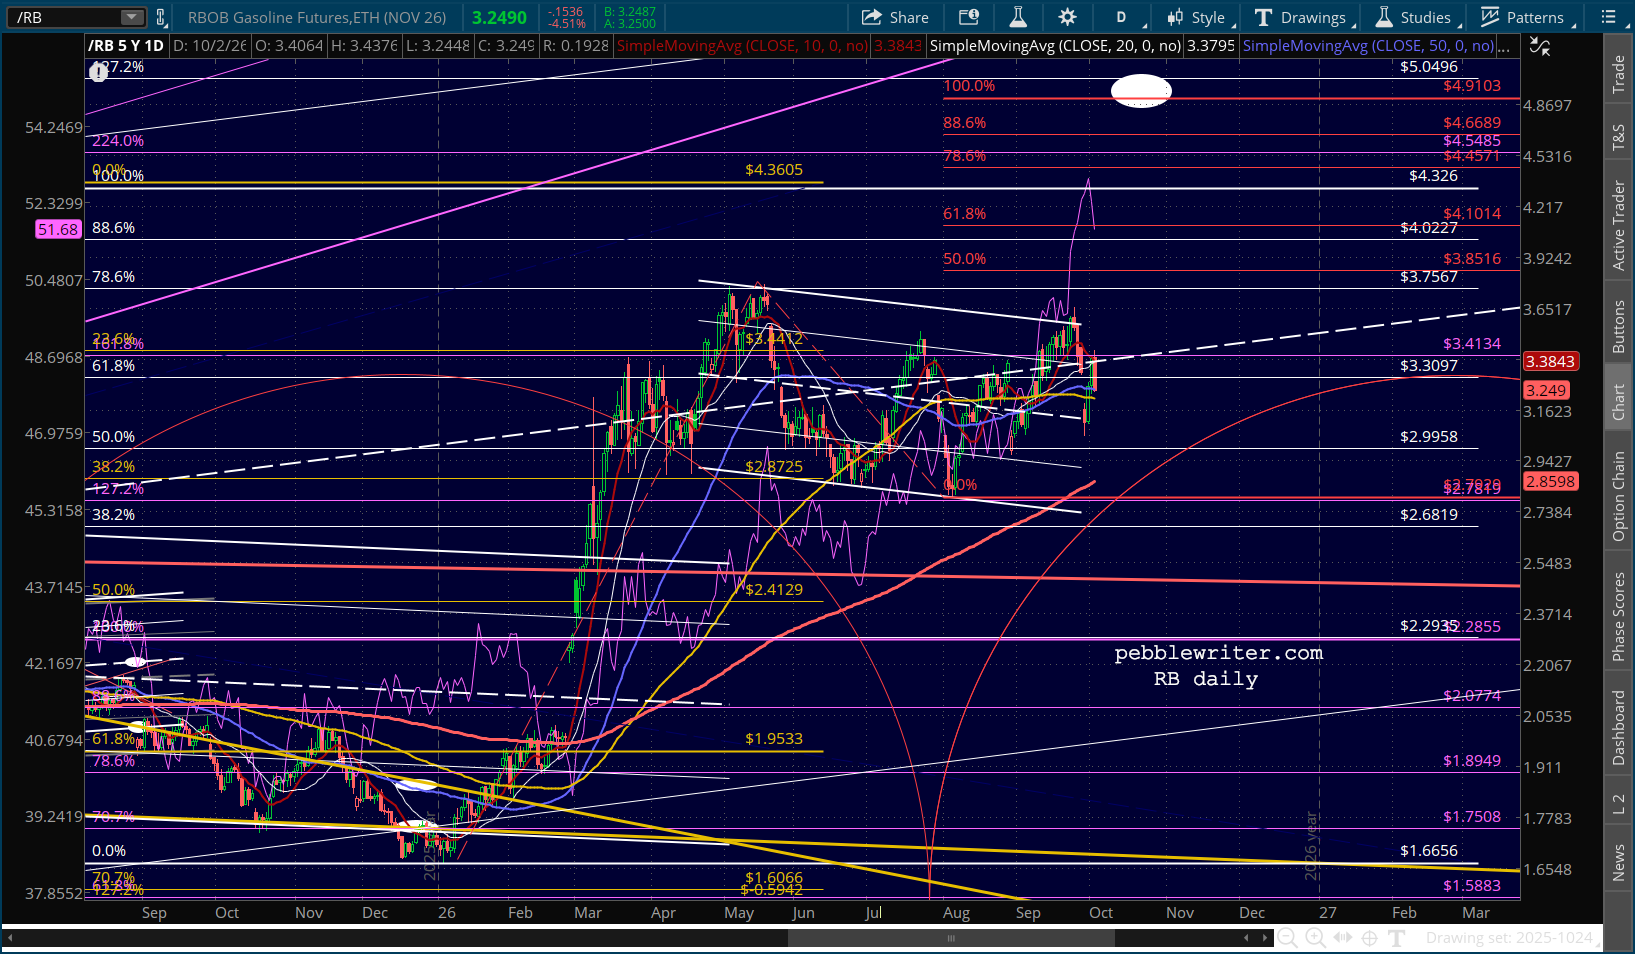
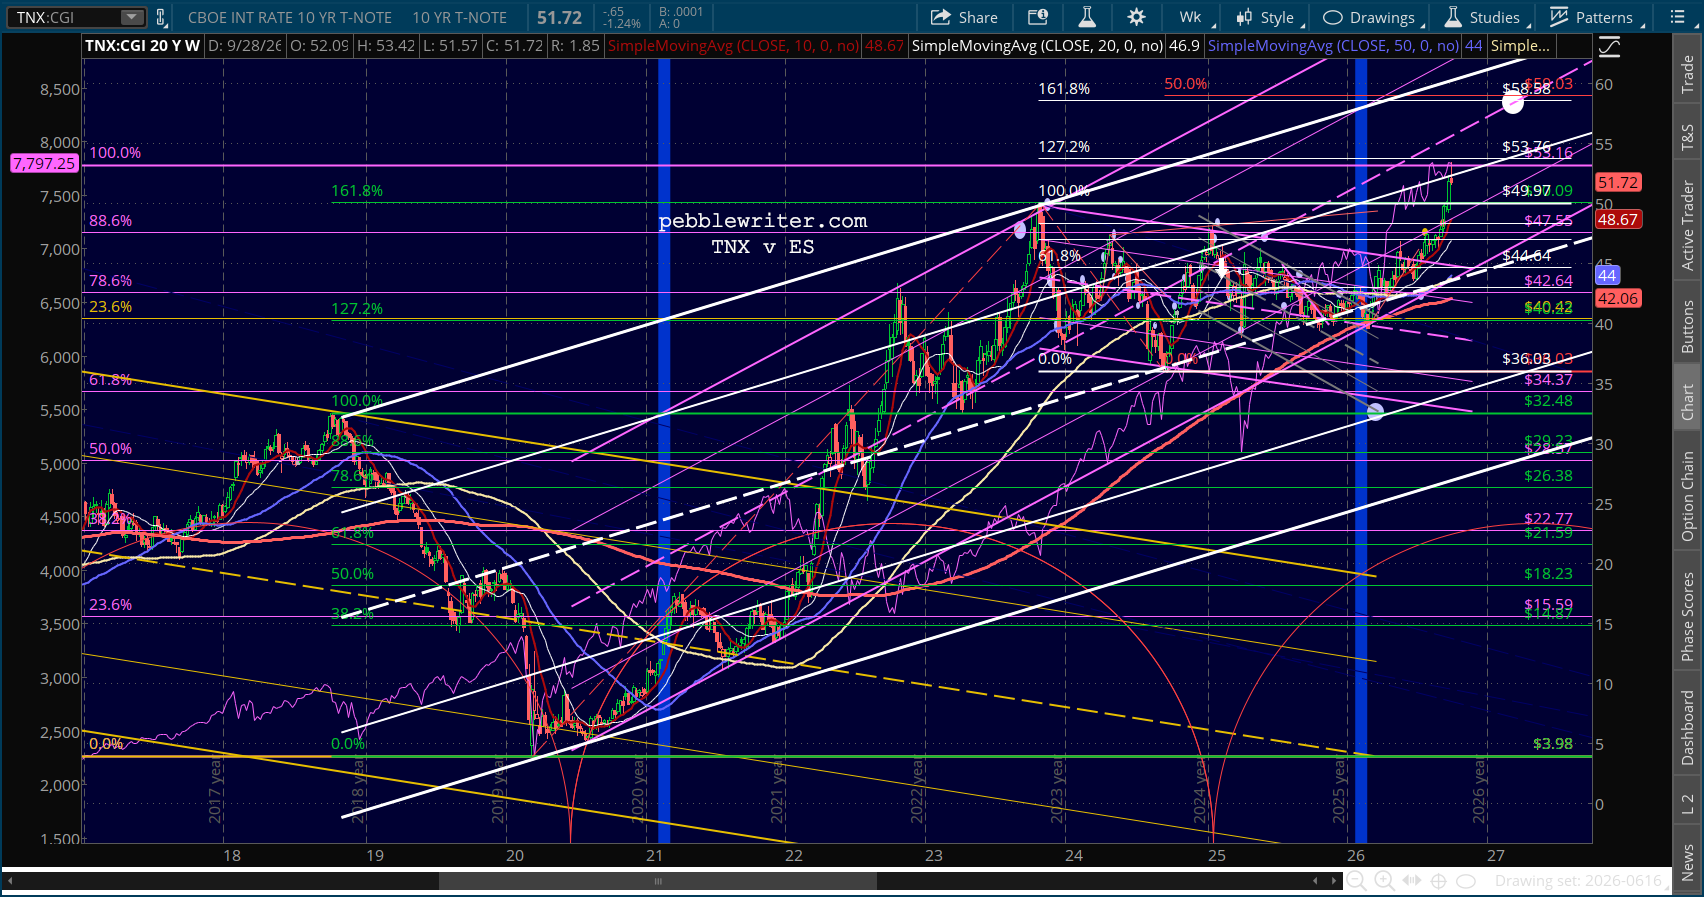
Because I took 10 years out of my finance career to write screenplays, I have an admittedly overactive imagination. While I have the MBA/CFA training and decades of actual Wall Street experience, I have no trouble imaging scenarios that are much darker than those offered by the talking heads on CNBC. With that proviso in mind, this is the scenario for the next 5 years that keeps me up at night. There are worse ones, but this one is arguably more plausible.
*. *. *
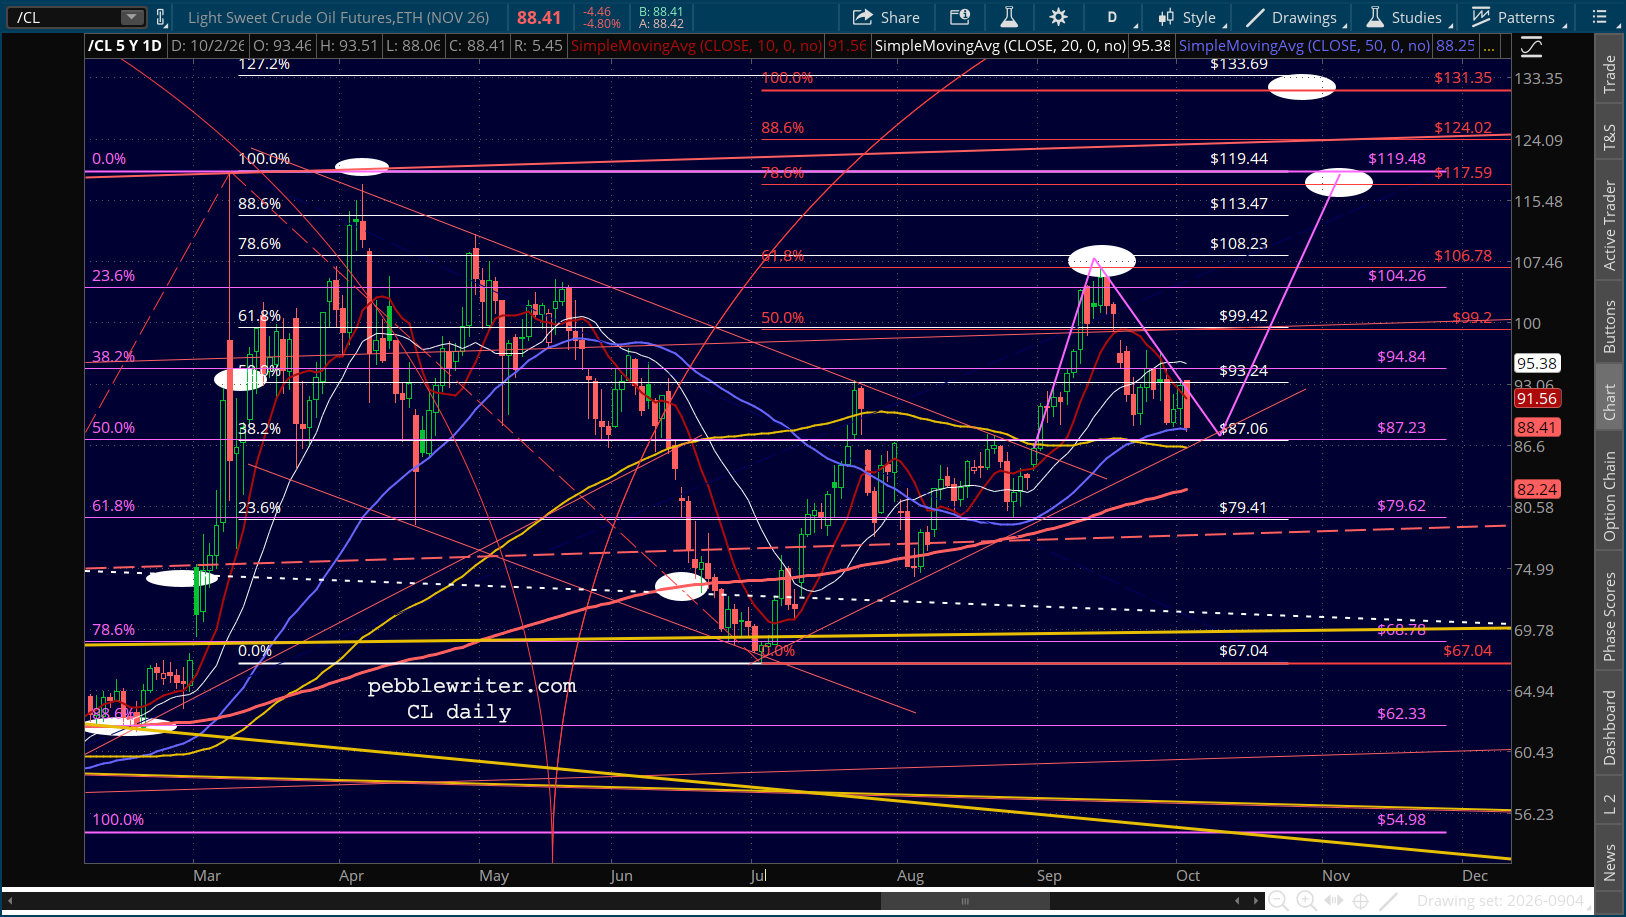
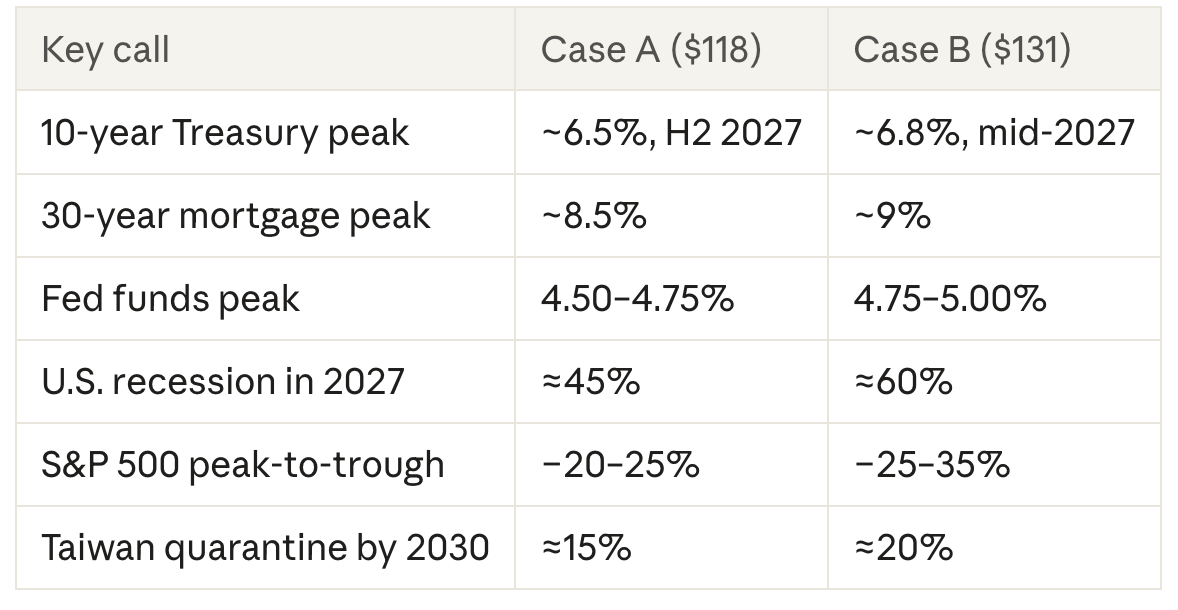
Assumption: Iran outmaneuvers Washington in the coming weeks, through drone strikes on Gulf export infrastructure and selective passage through Hormuz, and WTI rises from ~$90 to $118 (Case A) or $131 (Case B) by early November.
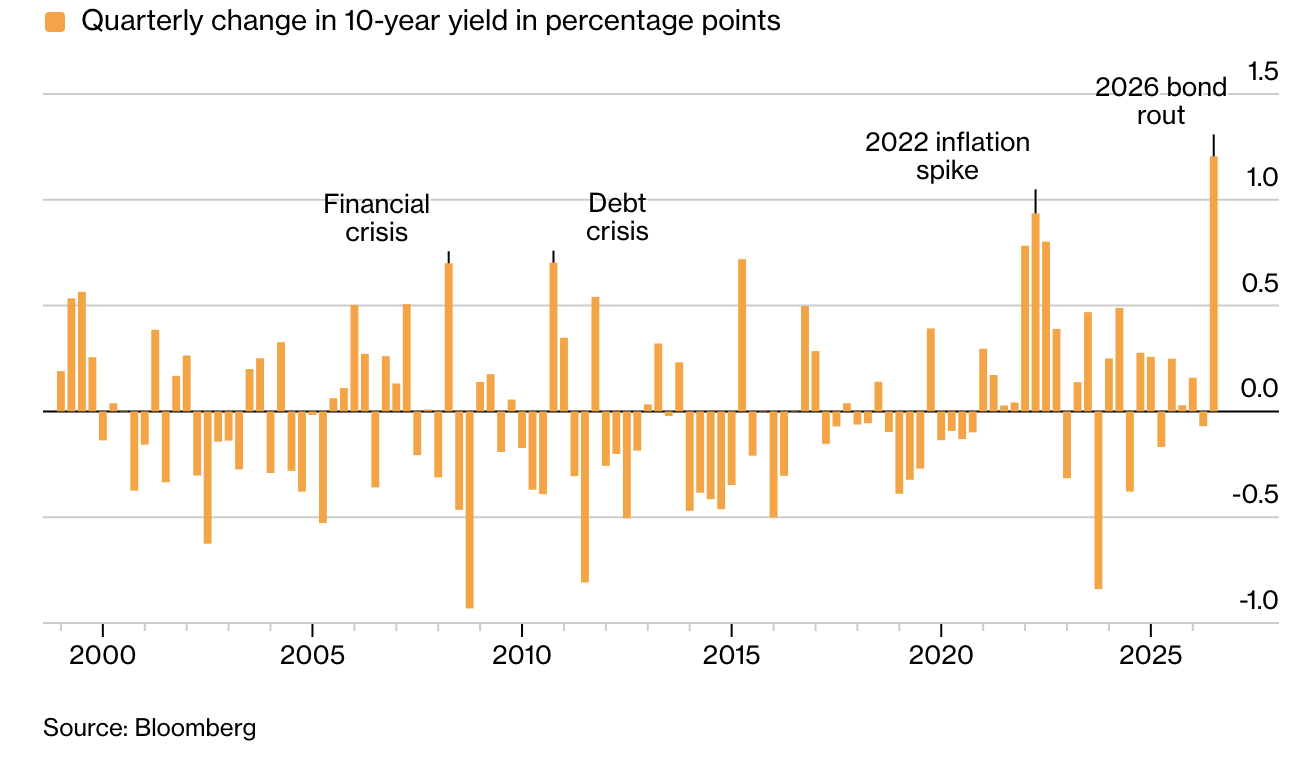
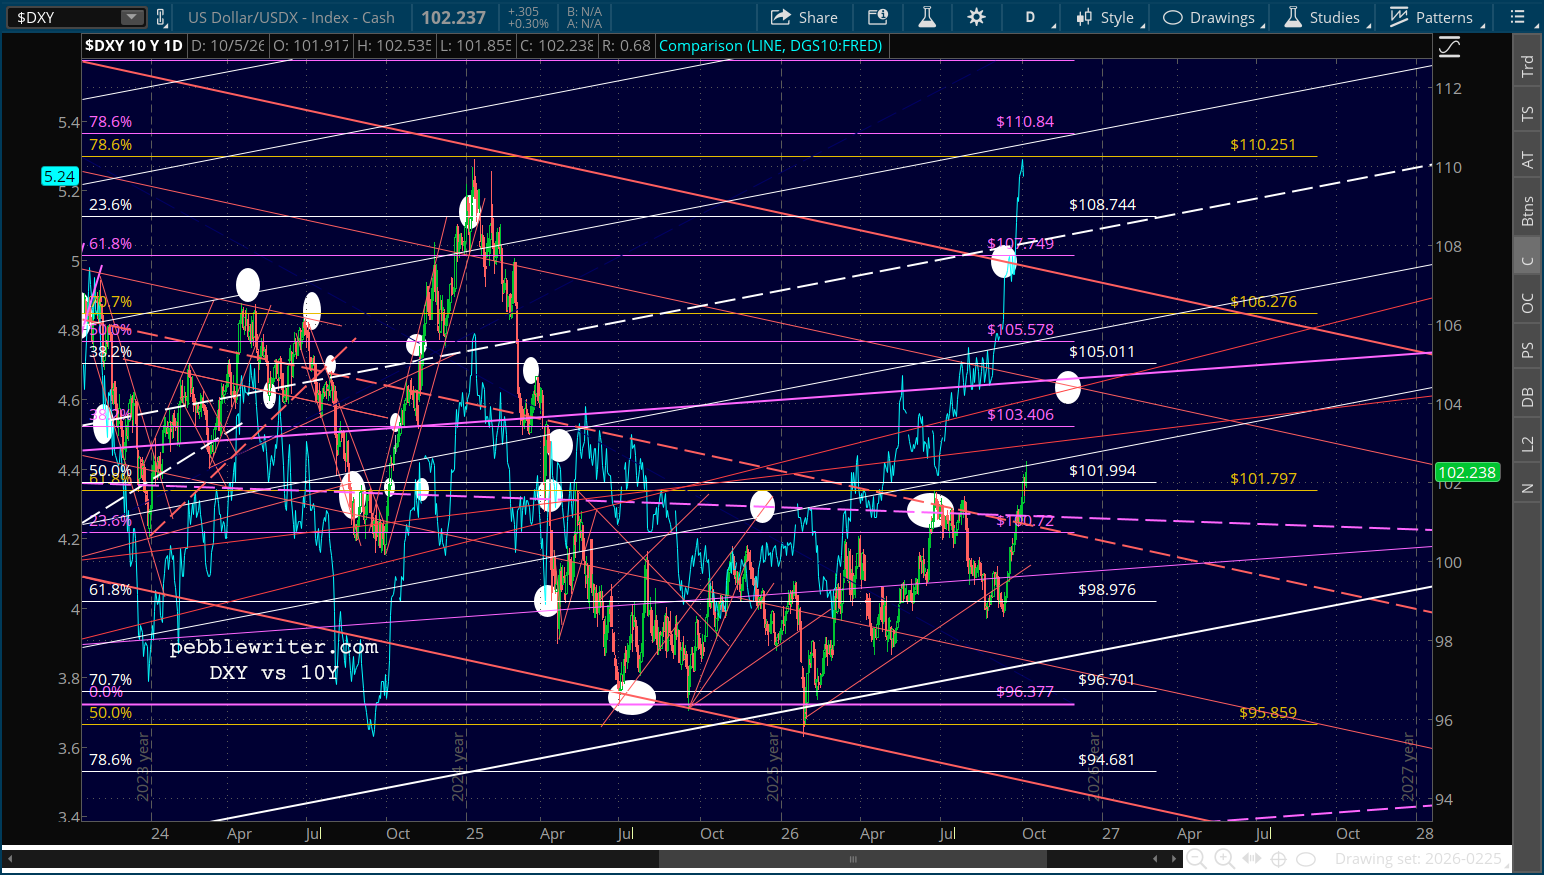
Thesis: The oil shock exacerbates 3% inflation, the Fed in hiking mode, a 10-year at a 24-year high and debt above 100% of GDP. It pulls the bond market’s peak forward to 2027, likely triggers a recession, and forces Washington into mild financial repression by 2029–30 in order to manage the growing debt.
How it Would Get Ugly
- Russia–China coordination. Russia gains an oil windfall; China, facing a larger import bill, leans on Russian and Iranian supply paid in yuan and gold. Expect joint patrols near Alaska and Japan and gray-zone pressure in the Baltic, but likely no formal alliance. The worse-case scenario contemplates an opportunistic formal alliance that takes advantage of the depletion of US arms.
- AI in markets. Correlated trading algorithms make a Treasury flash event likely (≈50%), and deepfakes or payment-system attacks are a real risk (≈35%). AI-driven job cuts deepen the recession and drive sentiment to new lows.
- AI at war. Cheap autonomous drones are how Iran effectively wins the war. By 2030, lethal engagements without real-time human approval will be commonplace. The tail risk is an AI early-warning false alarm in a crisis involving Russia and/or China.
What to Watch For
Q4 2026: oil spikes, midterms held amid high gasoline prices, Fed hikes in December. 2027: debt ceiling binds (~May), 10-year peaks, recession begins. 2028: X-date fight (~February), yields fall, stocks bottom early, presidential transition is the peak window for Taiwan risk. 2029–30: policy holds the 10-year near 4.5–5% while inflation runs 3.5–4.5%, so bondholders’ real returns turn negative.
Watch: WTI in December (below $100 means the squeeze failed; above $140 means worse); the 5-year inflation forward (above 3% signals unanchored expectations); auction tails and Japanese selling; the debt-ceiling timeline; and any week in which Russia and China move in the Baltic and around Taiwan at once.
Bottom line
No Treasury default, no U.S.–China war, no dollar collapse, but a costly replay of the 1970s: a 2027 yield peak, a recession, and years in which inflation shrinks the real value of the debt – and of savers’ bonds. The downside tail is oil above $140, a missed Treasury payment, or a military false alarm, any of which would push the outlook toward the darker case.